South Granville 2142 · Cumberland City
Duplex Builder in South Granville: How Duplex Finance Works
The duplex is approved. Now the bank has to agree.
South Granville's post-war blocks near Granville station make good duplex sites. The part owners underestimate is the money: how a construction loan pays the builder in stages, what the bank's valuer checks, and why anything outside the contract comes out of your pocket first.
Short answer
How does duplex construction finance work in South Granville?
A construction loan pays the builder in stages, usually deposit, slab, frame, lock-up, fixing and completion, each released after the lender's valuer checks the work. NSW caps the builder's deposit at 10% of the contract. Variations and extras can outrun the loan, so lock decisions in early. Cumberland DAs take 10 to 14 weeks, and building costs about $2,270 to $2,730 per m².
Written and reviewed by Oliver Alameri
Licensed builder, NSW Contractor Licence 487805C · Founder, Buildana
Fact-checked
How a construction loan actually pays out
A construction loan doesn't hand over the full amount on day one. It releases money in stages as the build progresses, and you usually pay interest only on what's been drawn. That keeps holding costs down during the build.
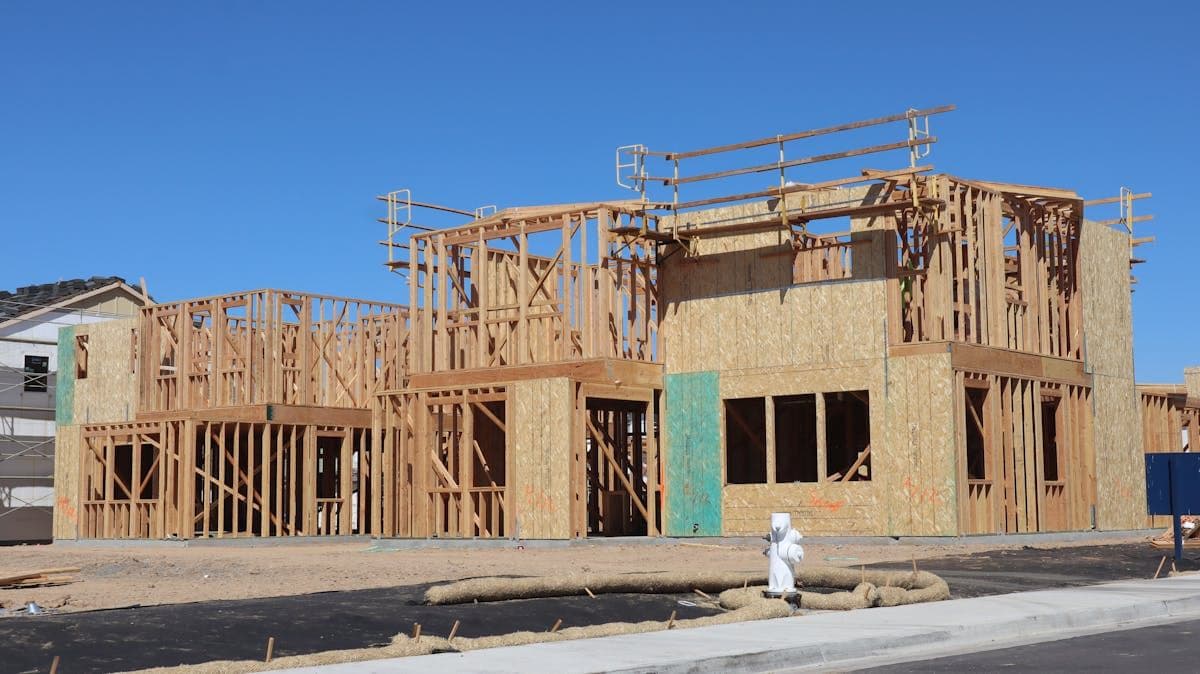
In NSW the stages normally line up with the building contract. A deposit, capped at 10% by the Home Building Act. Then base, when the slab is down. Frame. Enclosed, when the walls, roof and windows are in. Fixing, when internal linings, joinery and fit-off are done. Finally practical completion.
At each stage we issue a progress claim, the lender's valuer inspects, and the bank pays. Valuer not convinced the stage is finished? The payment waits. Days, sometimes weeks, while trades sit idle, which is exactly why stage definitions in the contract need to be precise.
- Deposit, no more than 10%
- Base: slab poured
- Frame: frame complete and inspected
- Enclosed: roof, walls and windows in
- Fixing: linings, joinery and fit-off
- Practical completion and handover
The bank pays for what its valuer can see. Build the stages so they're obvious.
What your lender will want from the builder
Most lenders ask for a fixed-price building contract, the council or certifier approval, the stamped plans and specifications, and a Home Building Compensation Fund certificate before they'll approve the loan. Some also want a builder's licence check and a progress payment schedule.
The valuer then values the property as if the duplex were complete, using the plans and the contract. If that valuation comes in low, the loan amount drops and the gap has to come from somewhere else. A detailed, realistic contract helps the valuer see what's being built.
Need a quote your lender will accept?
Share the South Granville address and your plans. I'll prepare a fixed-price duplex contract with site costs included and a stage schedule your bank can work with.
0476 300 300Why variations and extras hurt
The bank lends against the contract. Anything you add later, an upgraded kitchen, a pool, a different tile, isn't in the loan. You pay for it yourself, usually before the bank releases the next stage.
The same goes for costs a cheap contract left out: demolition, asbestos, site works, driveways, landscaping. That's the reason I price those upfront. A contract that looks cheaper but leaves out real costs can leave you short at the worst possible time.
On a duplex there are two of everything. So the gaps double too.
South Granville specifics
South Granville carries both R2 and R3 land. Whether two dwellings are allowed comes down to which of those you're on, plus the lot's size and street width under the Cumberland LEP 2021. Near Duck River, check for flood mapping. Slabs? Simple enough on this Class M ground.
Plenty of the houses went up between the 1950s and 70s, so demolition starts with an asbestos test. Cumberland Council usually needs 10 to 14 weeks for a DA.
Cost: roughly $2,270 to $2,730 per square metre for mid-spec work here, being the Rawlinsons Sydney rate lifted 3% for this area. With a fixed price and clear stages, your lender has exactly what it needs.
Finance checklist for a South Granville duplex
Have these ready and the loan approval moves much faster.
- 01
A fixed-price building contract with all site costs included
- 02
Council or certifier approval and stamped plans
- 03
The builder's HBCF insurance certificate
- 04
A clear progress payment schedule matching the lender's stages
- 05
Funds set aside for anything you plan to add outside the contract
- 06
Your plan for each half: keep, rent or sell
Duplex finance questions
How does a construction loan work for a duplex?
The lender releases funds in stages as the build progresses, usually base, frame, enclosed, fixing and completion. A valuer inspects before each payment, and you typically pay interest only on the drawn amount during construction.
How big a deposit can a NSW builder take?
Ten per cent of the contract price is the ceiling for residential building work under the Home Building Act.
What if the bank valuation comes in low?
The loan may be reduced, and the difference has to be covered from your own funds. A detailed contract and realistic plans help the valuer assess the finished duplex properly.
Can I add upgrades during construction?
Yes, but items outside the original contract usually aren't covered by the construction loan, so you pay for them directly.
Sources and references
Costs are from the Rawlinsons handbook with the local cost index applied; rules and timeframes are checked against the sources below.
A contract your bank can fund, with no surprises.
A South Granville duplex priced properly from the start, so the finance works stage by stage.